The assessment of the 2025-2026 campaign
This campaign was marked by:
a catastrophic olive harvest due to intense drought and the explosion of violence from the occupying army and settlers throughout the West Bank. It’s a -70% harvest in the West Bank: 7,000 tonnes compared to an average of 22,000 tonnes.
An increase in costs: particularly for olive oil due to the very low production (price increase of 30%), difficulties in transportation, and rising fuel costs.
Increased difficulties at several stages of the supply chain: severe insecurity and movement restrictions in the West Bank, a context of war against Iran complicating land and maritime logistics, banking and customs obstacles in France, rising fuel costs.
Significant changes in partner organisations (change of management and staff at Al Reef, liquidation of Andines and creation of Ekitopi).
Despite this, thanks to everyone's efforts, we managed to fulfil all your orders and achieve a record order volume!
Key figures:
Total amount sent to Palestine for the campaign: nearly €640,000.
Number of participants in pre-orders: about 130. That’s 30% more than in 2024-2025.
Prepaid share compared to the total ordered: about €400,000, or 2/3 of the total value.
Focus on dates:
8,200 kg of dates imported, of which nearly 40% are organic. That’s 32% more than in 2024-2025.
€120,000 paid to our Palestinian partners. That’s 40% more than in 2024-2025.
Focus on olive oil:
27,000 L of imported olive oil, of which just over half is organic. That’s 35% more than in 2024-2025.
€480,000 paid to our Palestinian partners. That’s 60% more than in 2024-2025.
The distribution of value in the sector: Case of olive oil*
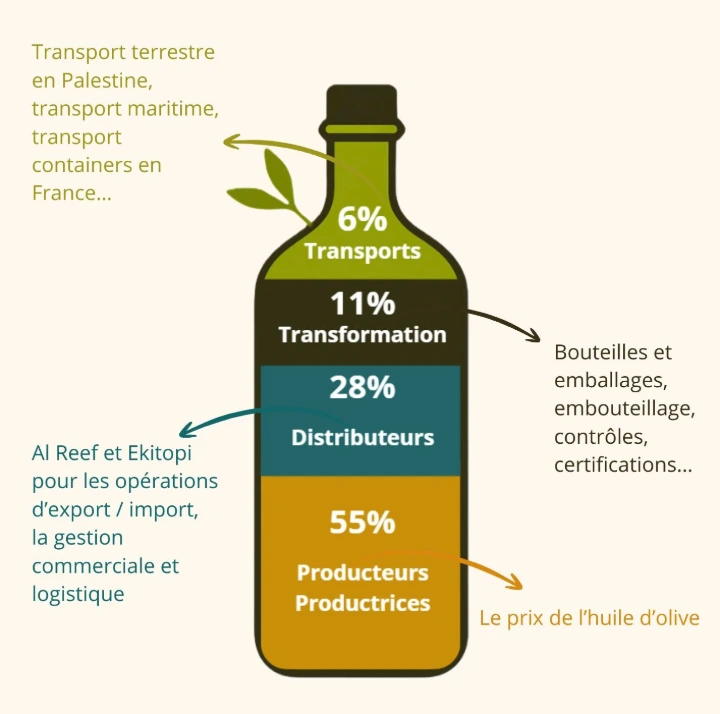
To summarise, when you buy a bottle of Palestinian olive oil at Ekitopi (excluding taxes):
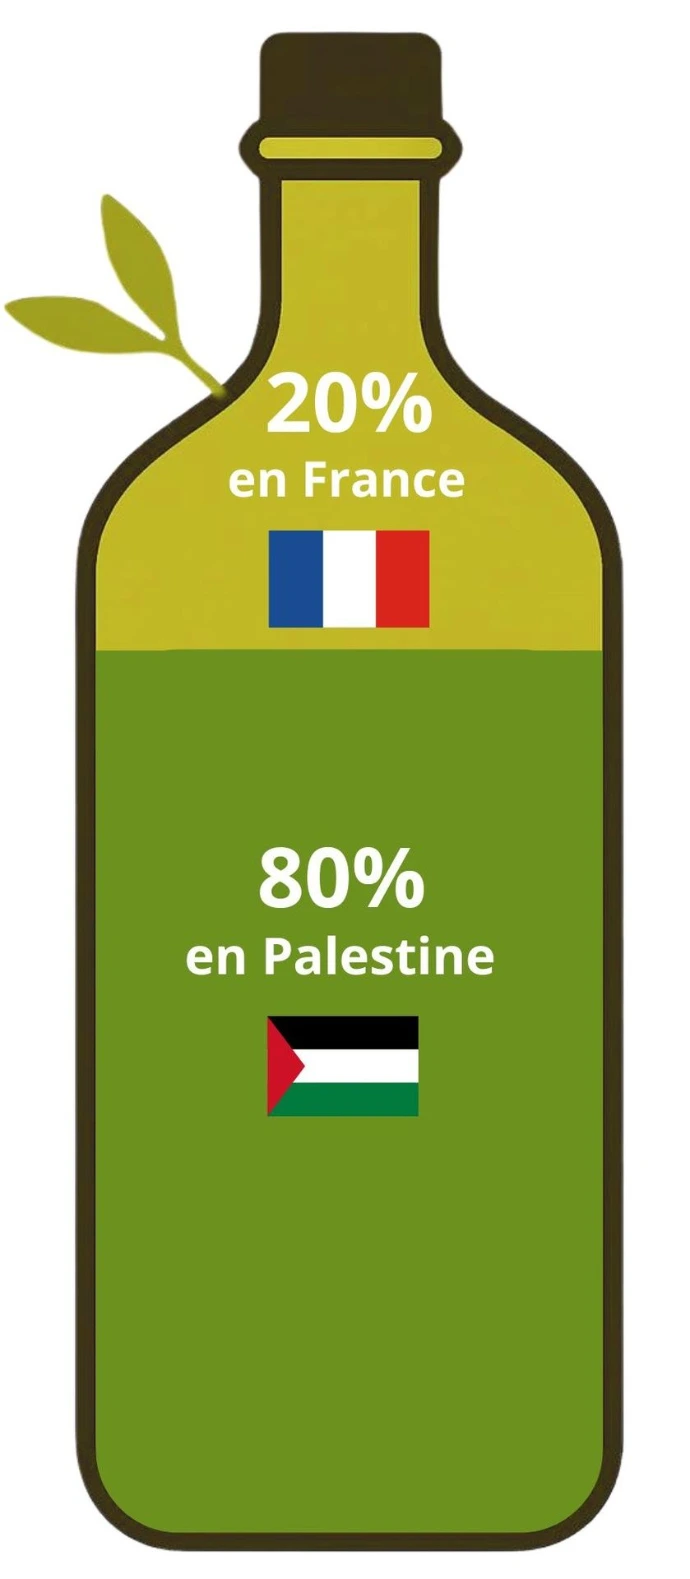
80% of the amount remains in Palestine and 20% in France.
Producers receive 55% - that’s the price of the oil.
Processing receives 11%. - bottles and packaging, bottling, controls, certifications…
Transport accounts for 6% of the cost - land transport in Palestine, maritime transport, container transport in France…
Distributors receive 28%. - Al Reef and Ekitopi for export/import operations, commercial and logistical management.
* these calculations do not include the cost of transport for deliveries in France.
According to the report of the Senate inquiry commission on the margins of industrialists and large retailers in the agri-food sectors published in May 2026, the distribution of value is largely unfavourable to producers who receive (excluding imports): 13% of the value for producers, 23% for industrialists and 64% for distribution.. To go further..
Distribution of costs for the Palestinian olive oil sector (figures for the 2025-2026 campaign)

* CIF = "Cost, Insurance, Freight". This price includes the selling price of the goods (C), the cost of insuring the goods during transport (I), and the cost of shipping the goods from the seller to the buyer's port (F).
As a reminder, organisations participating in pre-orders benefit from preferential rates. In 2025-2026, they received a 11.6% discount on conventional olive oil and 10% on organic oil. This discount is fully deducted from Ekitopi's share..
Value distribution table by country: Case of olive oil
Share PALESTINE | |
On price excluding pre-order | 86 % |
On price including pre-order | 77 % |
Average | 81.5 % |
Share FRANCE | |
On price excluding pre-order | 23 % |
On price including pre-order | 14 % |
Average | 18.5 % |
Value distribution table by link for the olive oil sector*
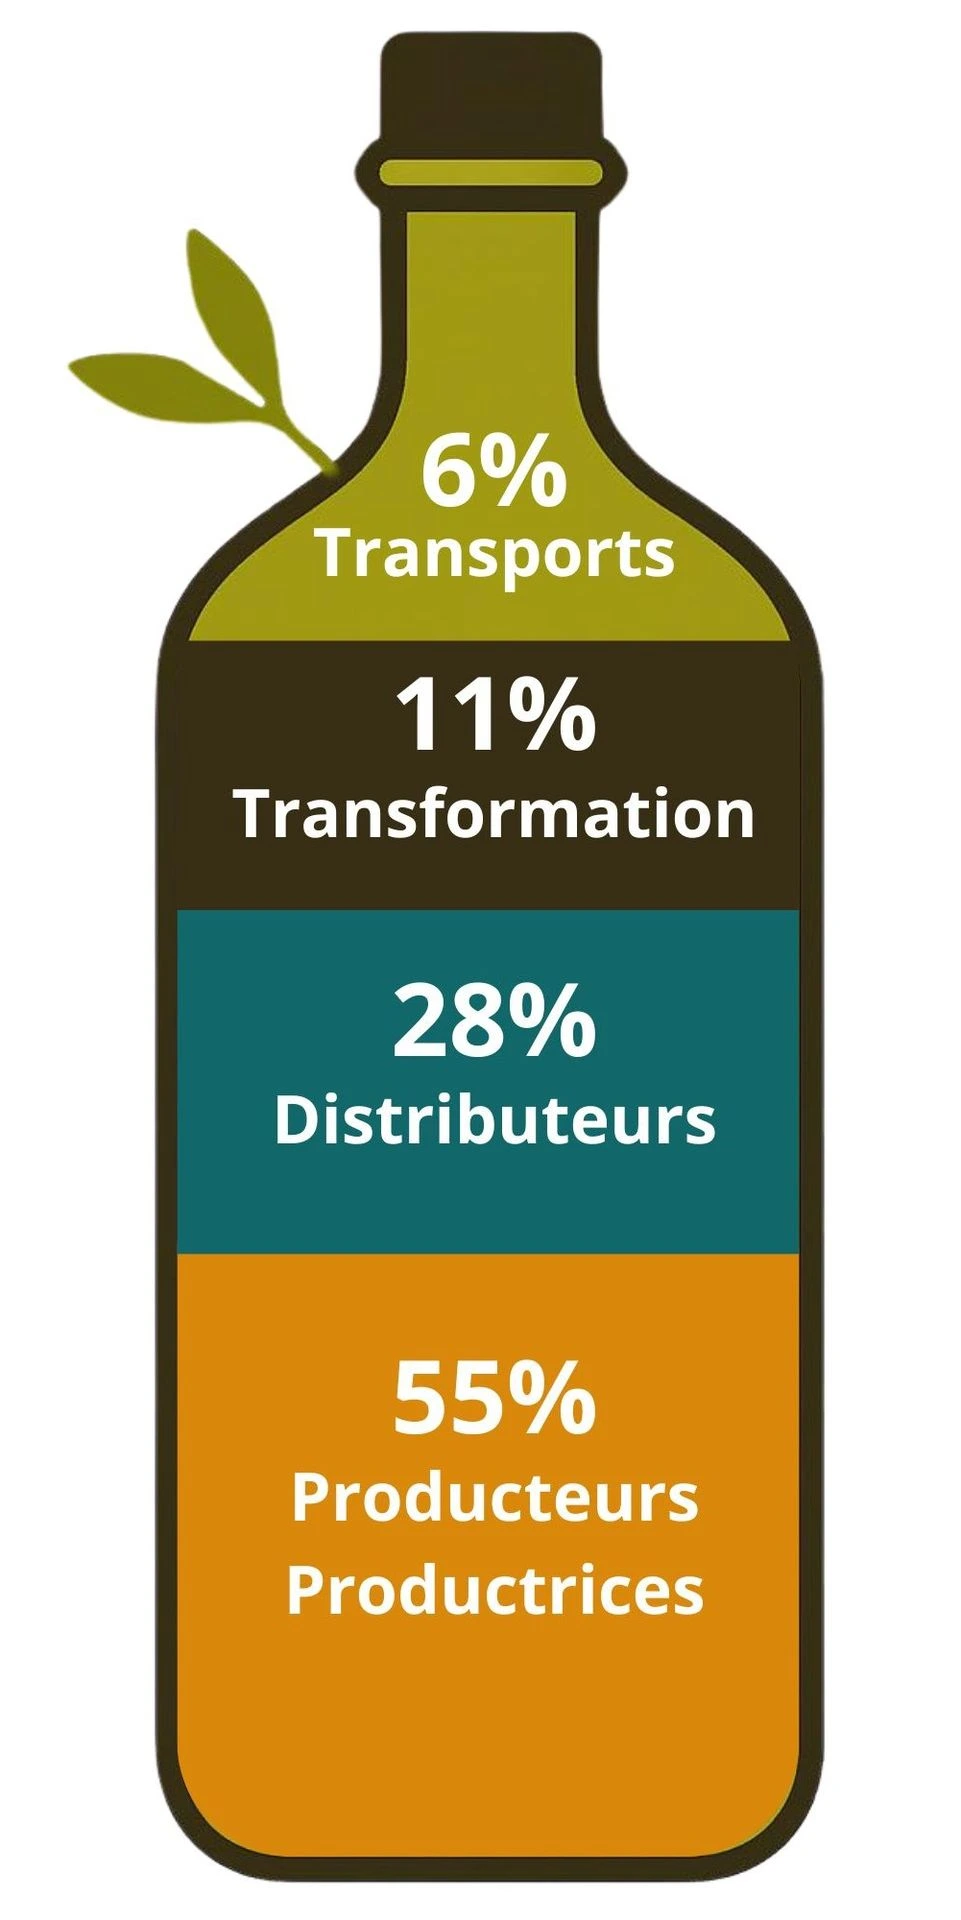
Who does what? | Link | Average share |
What farmers actually receive for the sale of their oil | Production | 54 % |
Includes oil pressing, packaging purchases, quality controls... | Processing | 11 % |
Includes all transport operations necessary from the olive groves to the Ekitopi warehouse | Transport | 6 % |
Includes all expenses related to export, import and marketing of products. | Distribution | 29% |
According to the report of the Senate inquiry commission on the margins of manufacturers and large retailers in the agri-food sectors published in May 2026, (imports excluded), the distribution of value is largely unfavourable to producers who receive (imports excluded): 13% of the value compared to 23% for manufacturers and 64% for large retailers. To go further.